
In early 2022, U.S. inflation as measured by CPI peaked at 9.1% and gold broke over $2,000/oz just like it is supposed to, right? Gold, as a real asset, has that long reputation for being a hedge against inflation. This reputation was really solidified in the 1970s and early 1980s, which I always thought might be a bit spurious. Inflation was very evident in the 1970s and gold went up a lot. But gold had been at an artificially fixed price for many decades prior to the 1970s, so a good chunk of that appreciation may have been it finding its real price after being manipulated for decades. Worth noting the gold to inflation correlation has fallen each decade since the 1970s and so far in the 2020s, it has actually been negative. Inflation is a heck of a lot lower than 9% today and gold is much higher.
One rule with gold investing: be prepared to be confused as its behaviour is often hard to explain. For evidence, let’s look at a gold model that we ‘borrowed’ a few years back [borrowed is a fancy way of saying we saw it and rebuilt it ourselves]. It was smart and intuitive incorporating many widely accepted drivers for the price of gold. This includes the U.S. dollar, real yields, inflation as measured by 2-year break evens, the VIX as a proxy for broader unease and gold ETF flows. The dollar and real yields carried the most influence. And let me share, this model was awesome for almost two decades. Look at how tight the model vs gold price remained from 2004-2021.
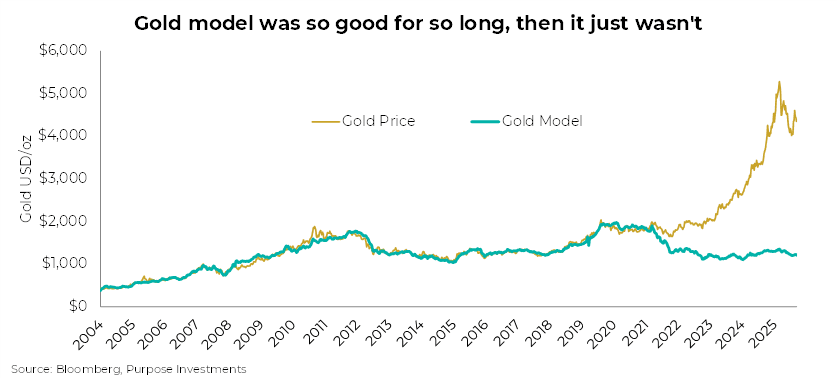
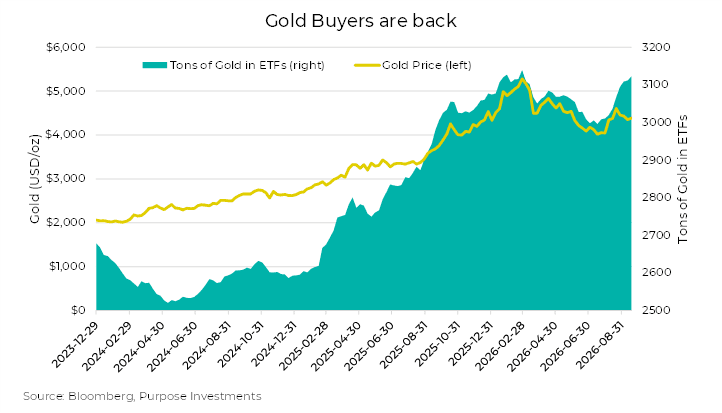
One of my early bosses was pretty emphatic that in the quant world building the model is easy, understanding it and when it may stop working is the skill separator. Safe to say that old gold model is broken. Training up a new gold model after 2021 using the same input factors fits well with the rise in gold, but with much different factor weights. The U.S. dollar is still a meaningful influence, but real yields flipped direction, which does sound suspect. The other big difference is ETF flows have become a much bigger factor in explaining the moves in gold. The good news of late, with all this talk about debt sustainability, inflows into gold bullion ETFs has resumed.
There was a time that talking gold only appealed to a few investors. But now for any Canadian it has become a performance driver for the TSX Composite. Gold miners have a 13.7% weight in the TSX, that is bigger than Utilities, Consumer Staples, Consumer Discretionary, Communication Services and Real Estate combined. The Materials sector, which is dominated by gold and silver miners, is larger than Energy. So, you best have an opinion as it’s too big to ignore.
We remain constructive on gold miners and bullion. The Canadian Gold index (TSX Gold Sub Industry Index) is obviously up a good amount over the past few years, but much of this has been thanks to strong earnings growth. Based on consensus estimates for the next 12-months, the index is trading at 13.6x. The valuation is even a bit more compelling given in 2026 earnings are forecast to be $325 and growing to $395 next year. 21% growth with a PE ratio below 14x is a good combo, acknowledging these earnings are very sensitive to oscillations in the price of gold.
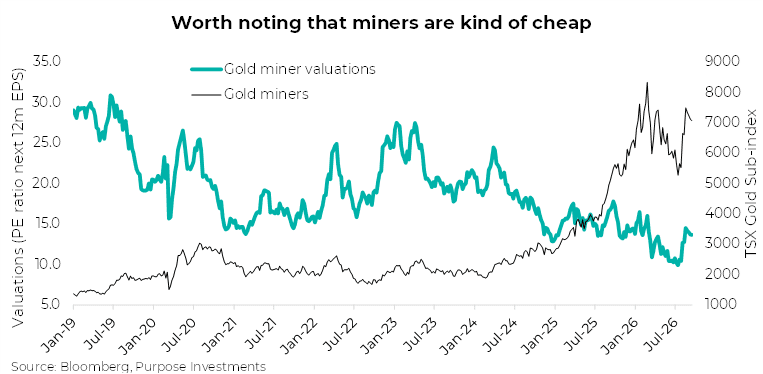
In late July, we added to our existing gold miner exposure in our North American dividend mandate, well timed (hats off to our co-portfolio manager, Derek Benedet). While nowhere near the TSX weight, at 5-6% we are certainly on the high end among dividend strategies. After the recent run, prices may be a bit stretched in the near term. But it does offer a good diversifier.
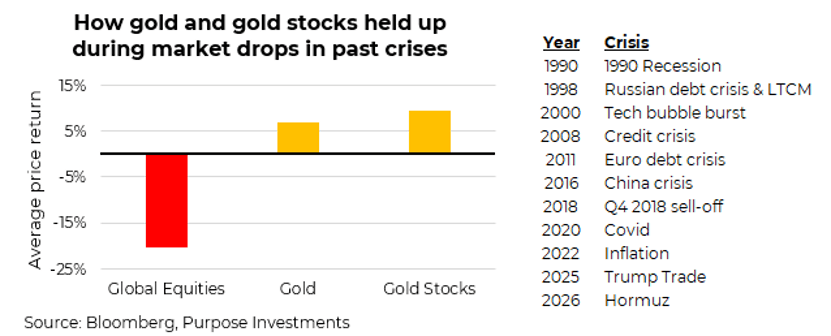
For bullion, we also have a positive view. It is a diversifier that has a very strong track record. The chart below tracks most major drops in global equity prices since 1990. Measuring the drop in equities, peak to trough, compared to the drop in gold bullion and gold miners. Certainly in times of trouble gold has a good track record. It is not lost on us that during the market weakness earlier this year with the conflict around Iran gold did not deliver. Nothing works all the time.
As we have highlighted in past Market Ethos, we are not overly concerned about global debt risks. That being said, it is a bit higher risk today than in years past. And we believe gold should be a good diversifier in case this risk does ramp. So, there you have it, constructive on gold miners with the caveat they have run a lot over the past few weeks. And a bit more constructive on bullion as a portfolio diversifier. Now let’s talk ‘new gold’.
Bitcoin – New Gold?
Many refer to Bitcoin as “new gold” or “digital gold”, owing to it’s engineered scarcity. Based on our work, it isn’t new gold, it is Bitcoin. And that isn’t a bad thing, it does offer a unique performance profile. For the record, we use Bitcoin in some portfolios and own some personally. One of the challenges remains the history, as Bitcoin ten years ago is very different than Bitcoin today. The vehicles to access, size, price are all very different. This does make modelling its characteristics challenging.
In our team’s opinion, from a portfolio construction perspective, gold is crisis alpha and Bitcoin is a potential performance booster with unique volatility characteristics. If the market does go risk-off, such as in that past crisis in the chart above, Bitcoin has not provided solace. While it didn’t exist during the 1st half of those events, for the 2nd half of the list it did. And it fell, on average, a little more than equities during those episodes.
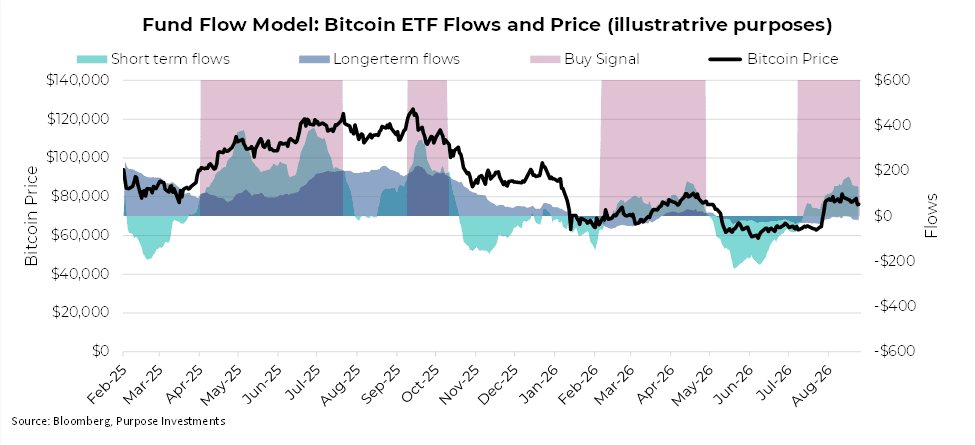
Now we do like our quant models, and we have built one for Bitcoin. It is predicated on the view with a somewhat fixed supply, variances in demand become the primary driver of price. To gauge deteriorating or improving supply / demand dynamics, we believe this will be captured in bitcoin ETF fund flows. Increased buying will show up in rising ETF issuance and vice versa. This model attempts to capture rising or falling demand/interest by investors in owning bitcoin. We don’t know if rising Bitcoin prices increases flows or if flows cause prices to rise. Regardless, this model appears to participate in upswings decently, while also avoiding some of those bigger downswings.
ETF flows are broken down into a longer-term average and a shorter-term moving average. When the shorter-term average is above the longer-term average, there is rising or accelerating buying. And when below, there is slowing buying or selling. Of course, news and overall market risk appetite are big factors in the price moves of Bitcoin, which are captured in aggregate investor behaviour via flows. This model is not systematic for us but helps guide our view on Bitcoin. It is currently bullish for Bitcoin after turning positive on July 31st, although flows have started to soften a bit.
Final Thoughts
Perhaps the biggest commonality between gold and Bitcoin is if you own either one, you had best be prepared to be confused at its behaviour. That may just be the reason they are diversifiers, with very different characteristics.
— Craig Basinger at Purpose Investments.
Get the latest market insights in your inbox every week.
Sources: Charts are sourced to Bloomberg L.P., as of September 18.
The content of this document is for informational purposes only and is not being provided in the context of an offering of any securities described herein, nor is it a recommendation or solicitation to buy, hold or sell any security. The information is not investment advice, nor is it tailored to the needs or circumstances of any investor. Information contained in this document is not, and under no circumstances is it to be construed as, an offering memorandum, prospectus, advertisement or public offering of securities. No securities commission or similar regulatory authority has reviewed this document, and any representation to the contrary is an offence. Information contained in this document is believed to be accurate and reliable; however, we cannot guarantee that it is complete or current at all times. The information provided is subject to change without notice.
Commissions, trailing commissions, management fees and expenses all may be associated with investment funds. Please read the prospectus before investing. If the securities are purchased or sold on a stock exchange, you may pay more or receive less than the current net asset value. Investment funds are not guaranteed; their values change frequently, and past performance may not be repeated.
Certain statements in this document are forward-looking. Forward-looking statements (“FLS”) are statements that are predictive in nature, depend on or refer to future events or conditions, or that include words such as “may,” “will,” “should,” “could,” “expect,” “anticipate,” “intend,” “plan,” “believe,” “estimate,” or other similar expressions. Statements that look forward in time or include anything other than historical information are subject to risks and uncertainties, and actual results, actions, or events could differ materially from those set forth in the FLS. FLS are not guarantees of future performance and are, by their nature, based on numerous assumptions. Although the FLS contained in this document are based upon what Purpose Investments and the portfolio manager believe to be reasonable assumptions, Purpose Investments and the portfolio manager cannot assure that actual results will be consistent with these FLS. The reader is cautioned to consider the FLS carefully and not to place undue reliance on them. Unless required by applicable law, it is not undertaken, and is specifically disclaimed, that there is any intention or obligation to update or revise FLS, whether as a result of new information, future events, or otherwise.


