
The largest development concerning markets over the past month has been the continuous rise in bond yields. The U.S. 10 year has risen to around 5.3%, eclipsing the 2023 highs and reaching levels last seen when Don Draper was fast becoming a household name (hint: 2007). Interestingly this was also where yields peaked prior to the financial crisis. Unlike other periods of surging bond yields, markets are largely taking this latest run-up in stride. The S&P 500 is playing it cool, off just a few percent from all-time highs. Like Don Draper, Old Fashioned in hand in a freshly tailored suit, the index is projecting strength, and an image of resilience that completely masks a deteriorating foundation and turmoil within. A closer look at market breadth reveals an internal growing divergence between the average stock and what you see in headline returns.
Market breadth is a broad term to describe the numerous ways to slice and dice the market to gauge market participation. Strong breadth is generally considered to be a healthier market, while narrow breadth indicates worsening internal participation. One of the more common gauges is the percent of index members trading above key moving averages such as the 50 and 200 days. As we write, just 44% are trading above their 200-day moving average, and 23% above the shorter term 50 day moving average. This is extremely low, and quite rare to have such poor breadth with the index just shy of its highs. We typically see these levels during corrective events, not just shy of the highs. If history is to be a guide, this type of setup typically resolves itself with prices moving down to breadth rather than breadth catching up to price.
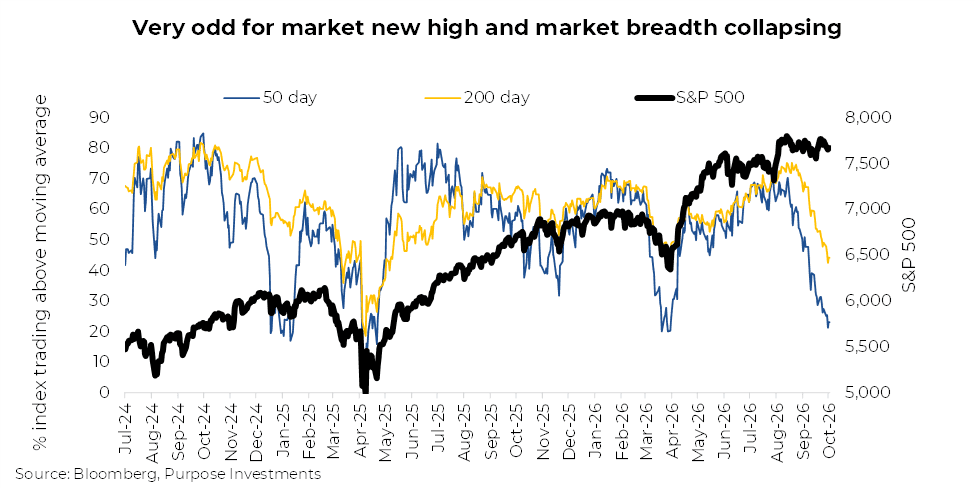
Other Breadth Stats - Like baseball commentators, market strategists can surprise you with novel statistics. New to us this week was the Goepfert stat (don’t worry, we’ve never head of this before either). The S&P 500 recently rallied at least 1% of a record, while more stocks hit new lows than new highs. This has only occurred on two other days in history: July 23, 1929, and December 21, 1999. Both instances came a few months before major market tops. Chilling, and with a sample size of two, it should be taken with a grain of salt. It’s more cocktail hour fodder, rather than market signal.
Other more conventional breadth measures are showing the same thing. The NYSE Advance/Decline line peaked on August 14th and has been falling for six weeks. Internals have been deteriorating for six weeks, and the most recent comparable episode with the index this close to a high was July 2015, which eventually resolved itself with a correction.
Heavy Hitters - Over the past month, nearly all sectors in Canada and the U.S. were in the red. The lone exceptions were Technology and Communication Services in the U.S. which is basically a Tech ride along. Concentration risk is real; however, those concentrated sectors are the only ones working at the moment, and that is precisely why the index looks fine.
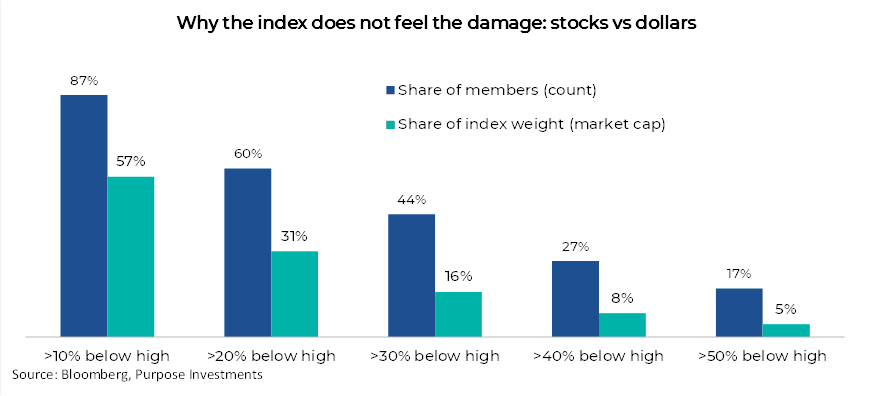
The majority of companies in the S&P 500 (60%) are already in a structural bear market, more than 20% below their all-time highs. This is a bear market for the average stock hiding in plain sight. That bucket is only 31% of the cap-weighted index. At the other end, just 66 stocks sit within 10% of their high. They are 13% of the members, but 43% of the weight. We see this same divergence in each drawdown tranche in the chart below. There is a stark difference in the share of members experiencing substantial drawdowns versus the index weight.
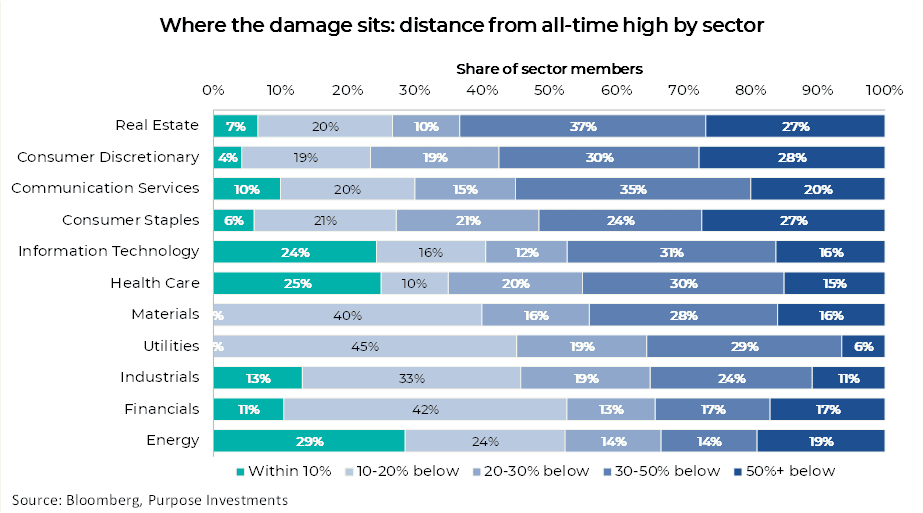
Digging a little deeper, the chart below breaks down the same drawdown tranches by sector. The damage is deepest in rate sensitive sectors. Roughly three quarters of Real Estate, Consumer Discretionary and Consumer Staples members are more than 20% below their all-time highs, and in Real Estate close to two thirds are more than 30% below. Staples, a sector investors normally look for stability has 27% of its members more than 50% off their highs. At the other end, Energy and Financials are the only ones where fewer than half the members are in a 20%+ drawdown. Technology is split in two. A quarter of its members sit within 10% of a record while 47% are down 30% or more. It just so happens that the quarter near the highs carry most of the index weight. This year only Energy (+37%) and Technology (+28%) are beating the S&P 500 (+12.7%) and only 35% of members are ahead of the index. Dispersion this wide should favour active managers; however, it is tougher when fundamentals are not driving the dispersion but sheer size, rate sensitivity and whether a company is deemed an AI winner or loser are the determining factors.
Portfolio Implications - Falling breadth is not automatically bearish. The best buying opportunities of the past 35 years all arrived when breadth was terrible, because price was already down. Breadth this weak with price still at the highs is a different animal, and historically worrisome one. Breadth alone should never be used for market predictions; however, it is alerting investors to proceed cautiously. Digging into the internals reveals more of a rate driven dispersion rather than a growth scare. Rate sensitives have been hit hardest. Credit spreads, volatility and earnings revisions all disagree with the breadth bears. For now, the macro backdrop is calm, earnings growth is strong, and the economy is still humming.
In terms of how the poor breadth is impacting portfolio’s, income mandates are being acutely impacted. The current environment is hard not only for traditional fixed income but for dividend portfolios carrying excess rate sensitivity. Weak internals don’t last forever, eventually something has to give. Give the degree of drawdown in many of the rate sensitive sectors valuations are becoming more attractive. Within our mandates we’ve begun to lean into the defensive/rate sensitive sell-off. The signs are clear, market fragility has risen, so we’re proceeding cautiously. If yields reverse, expect this to be the first catalyst for breadth to broaden, and we’d expect the beaten down rate sensitives to rebound appropriately. But now to dig deeper into the dividend space.
Cyclical Yield
So, we have a market that is holding up at the index level but underneath the surface most companies are simply performing rather poorly. For the S&P 500 23% of index members are trading above their 50-day moving average. Fortunately, the megacaps are largely in that 23% and performing well, given their heft in the cap weighted index and we have a market that is holding up. Same thing is happening in Canada with the TSX. Only 26% of members are above their 50-day moving average. Mitigating the impact on the headline index number isn’t technology, although it is helping, it is more so Energy and Materials. More economically cyclical parts of the market are doing well largely because the economic optimism has been on the rise and supply disruptions continue.
In the dividend space this is causing massive divergence. More interest rate sensitive dividend payers such as Utilities, Pipelines and Real Estate are really struggling with these higher yields. But more economically cyclical dividend paying companies are doing much better. Cyclical Yield is a framework we developed years ago to differentiate among dividend paying companies based on their sensitivity to yields. Interest Rate Sensitives are in sub-industries that correlated more so to changes in yields. Often these are the ones bucketed in the term ‘bond proxies’. While Cyclical Yield dividend payers are less sensitive to changes in yields usually because they are more sensitive to changes in economic activity, hence the term ‘cyclical’.
In the following chart, we have charted the relative performance of Cyclical Yield industries vs Interest Rate Sensitives. A rising line implies Cyclical Yield is outperforming. It is both intuitive and it works. As bond yields fell from 2010 to 2020, Interest Sensitives were the winners among dividend paying companies. But since 2020, it has been Cyclical Yield. As a result, portfolios with more Cyclical Yield have been doing better as yields move higher.
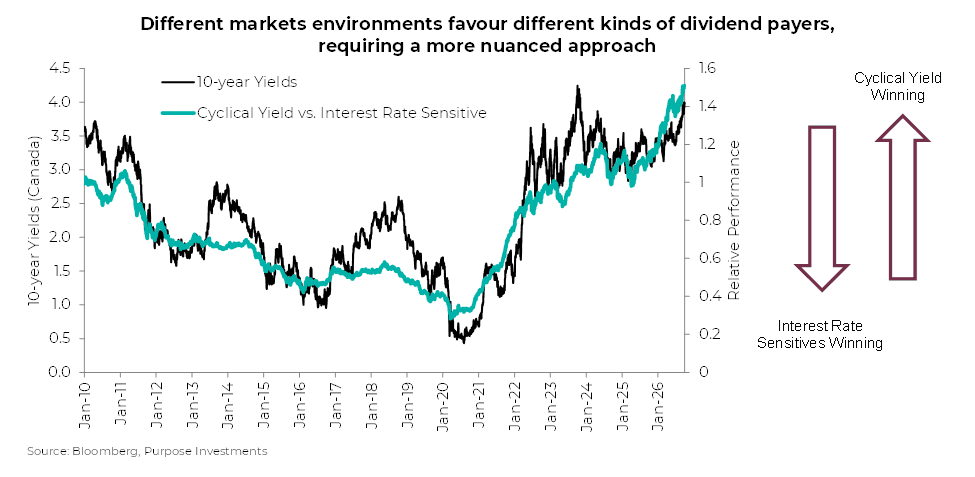
Going forward, things get a bit more complicated. The above line is relative performance, we should point out that while interest rate sensitives have lagged, they are still up over the past few years. Just not as much and has seen a dip with this latest rise in bond yields. What is starting to look interesting is the interest rate sensitives, that have historically traded with a slight premium valuation to the overall TSX are now roughly inline. Meanwhile, the average valuation among cyclical yield industries fluctuates a lot but has certainly rise of late.
We are still fans of cyclical yield over interest rate sensitives with a mix of about 60%/40% in our North American dividend mandate. But this view is starting to moderate as we are seeing some enticing value and improved risk/return potential among interest rate sensitives.
Market Cycle
Folks are pretty bent out of shape over this rise in yields and it is certainly a risk. But it is not all bad news. For one, equity markets are up this year and bonds are now flattish, isn’t that kind of how it is supposed to work? Plus, while these yields have moved higher due to a number of factors the dominant factor appears to be rising economic activity. That is one of the reasons markets have held up, higher bond yields driven by better economic data is perhaps ones of the best reasons for bond yields to rise.
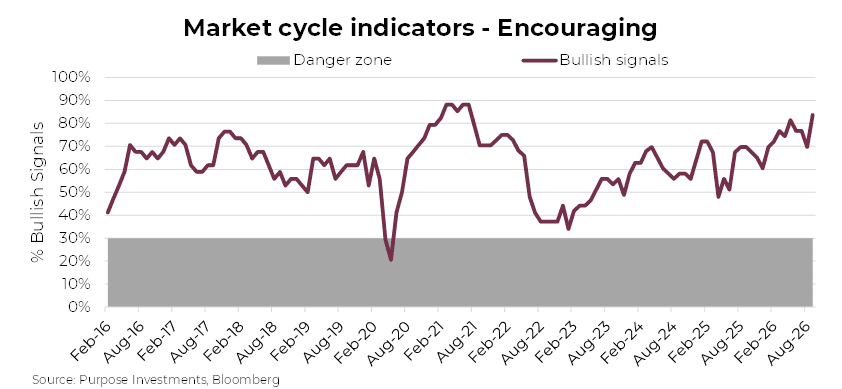
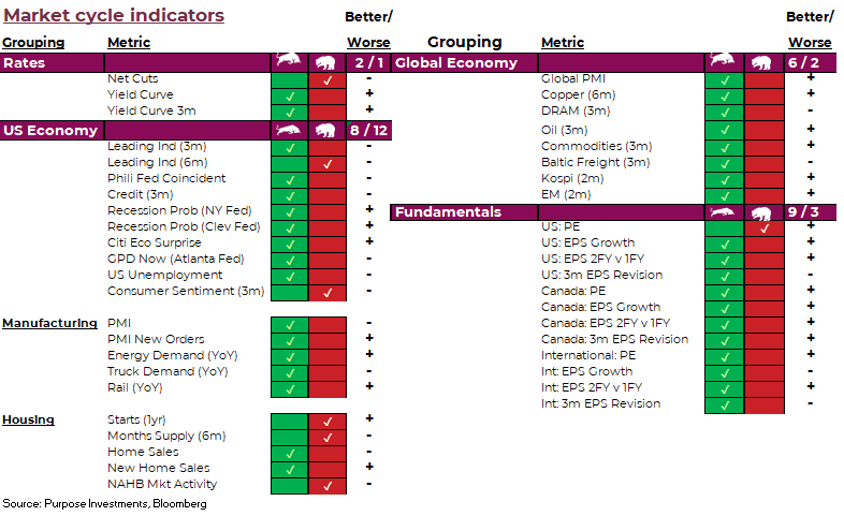
Not surprising, the better economic data is translating into a leg higher in our Market Cycle indicators. These cover economic data for the U.S. and Global Economy, plus valuations, earnings and rates. The only soft spot at the moment is U.S. housing, one of the parts of the global economy that is most sensitive to higher yields. Otherwise, it is pretty much a good news story everywhere.
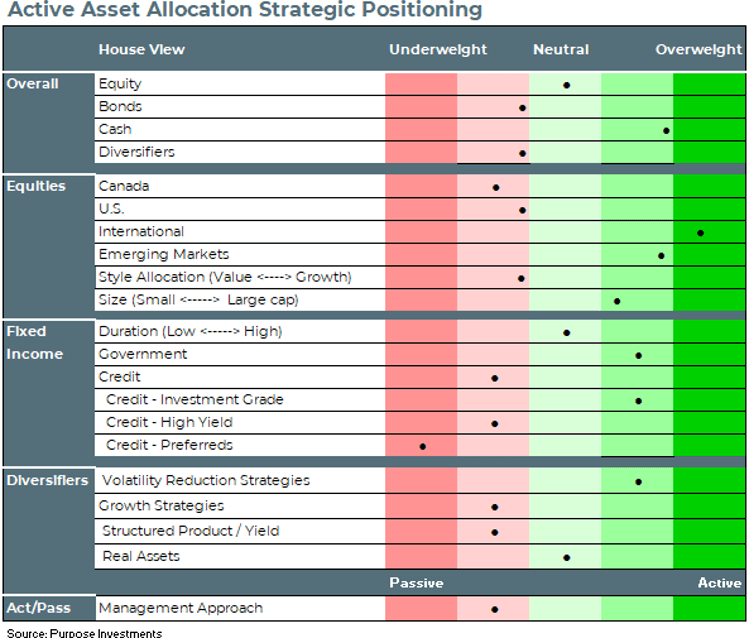
No change to our allocations over the past month. We remain about neutral on equities, largely because of the strong run already enjoyed. Bit underweight on bonds and holding extra cash. Among equities, we have a bit of an underweight in Canada and overweight internationally, with neutral tilt on the U.S. side.
Final Thoughts
Solid economic and earnings is helping these markets manage the higher yields and other macro concerns. But with breadth this weak, perhaps the market is starting to show some signs of strain after so many years of strong performance. Don’t get all bearish though, earnings season kicks off soon and the last one was a gangbuster. This could help provide more fundamental support for the market, and some lower yields would help too.
— Craig Basinger & Derek Benedet at Purpose Investments.
Get the latest market insights in your inbox every week.
Sources: Charts are sourced to Bloomberg L.P., as of October 2, 2026.
The content of this document is for informational purposes only and is not being provided in the context of an offering of any securities described herein, nor is it a recommendation or solicitation to buy, hold or sell any security. The information is not investment advice, nor is it tailored to the needs or circumstances of any investor. Information contained in this document is not, and under no circumstances is it to be construed as, an offering memorandum, prospectus, advertisement or public offering of securities. No securities commission or similar regulatory authority has reviewed this document, and any representation to the contrary is an offence. Information contained in this document is believed to be accurate and reliable; however, we cannot guarantee that it is complete or current at all times. The information provided is subject to change without notice.
Commissions, trailing commissions, management fees and expenses all may be associated with investment funds. Please read the prospectus before investing. If the securities are purchased or sold on a stock exchange, you may pay more or receive less than the current net asset value. Investment funds are not guaranteed; their values change frequently, and past performance may not be repeated.
Certain statements in this document are forward-looking. Forward-looking statements (“FLS”) are statements that are predictive in nature, depend on or refer to future events or conditions, or that include words such as “may,” “will,” “should,” “could,” “expect,” “anticipate,” “intend,” “plan,” “believe,” “estimate,” or other similar expressions. Statements that look forward in time or include anything other than historical information are subject to risks and uncertainties, and actual results, actions, or events could differ materially from those set forth in the FLS. FLS are not guarantees of future performance and are, by their nature, based on numerous assumptions. Although the FLS contained in this document are based upon what Purpose Investments and the portfolio manager believe to be reasonable assumptions, Purpose Investments and the portfolio manager cannot assure that actual results will be consistent with these FLS. The reader is cautioned to consider the FLS carefully and not to place undue reliance on them. Unless required by applicable law, it is not undertaken, and is specifically disclaimed, that there is any intention or obligation to update or revise FLS, whether as a result of new information, future events, or otherwise.


