
It’s a telltale sign of fall, that first step outside with a definitive crispness in the air. Before the leaves begin to turn their brilliant orange, red and yellow. Before pumpkins begin to show up on neighborhood doorsteps, it starts in the air. We can sense it immediately, it stirs something within signaling the season is changing.
Markets aren’t that different. The market moves through cycles, which we can observe by measuring trends of the market as well as what types of stocks are starting to outperform. We call this relative strength. Watching it is a bit like watching a wind vane swinging back and forth. Monitoring the movements is important since winds change before the weather does. This month, the vane has swung.
The Wind Vane: Defensives Take the Lead
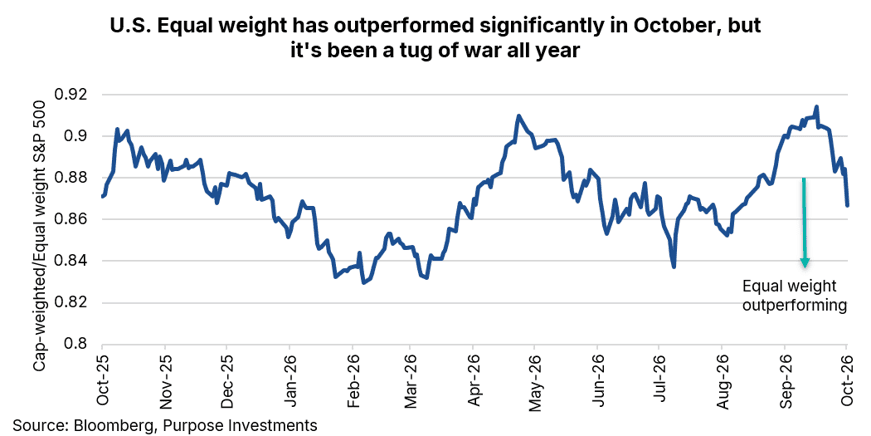
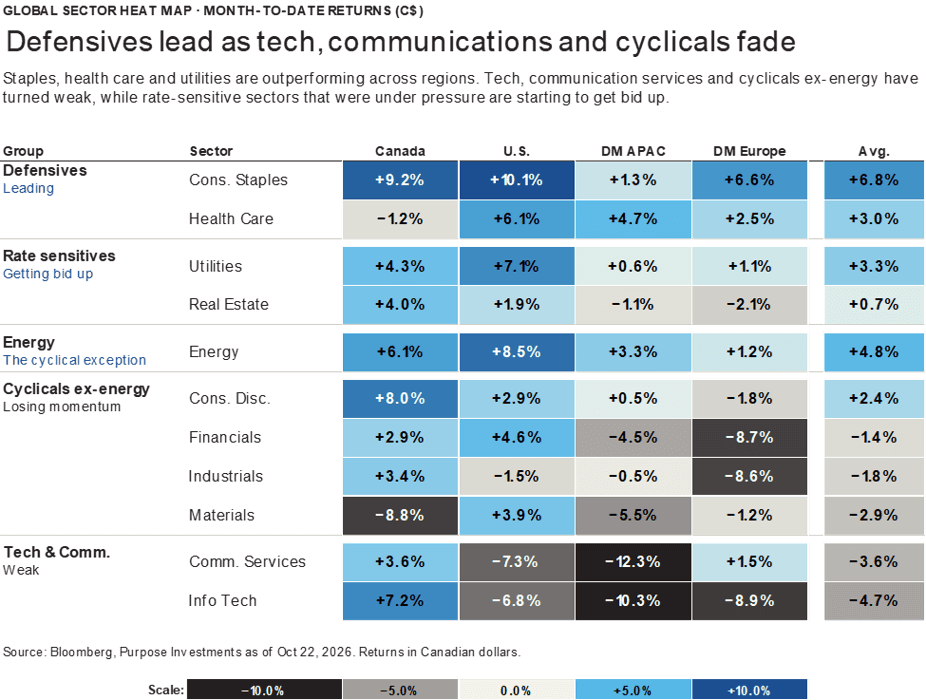
The clearest sign is the resurgence in S&P 500 equal weight versus the cap weighted index. Last month the tech heavy cap-weighted index surge; however, in October that reversed quickly. Month-to-date the equal weighted index is up nearly 5% (as of October 22, 2026) compared to the cap-weighted index which is now flat. The equal weighted index just had its strongest one-day relative move (+2%) in over two years on October 22. Two things are driving the change. The AI trade is still struggling to find firm footing, but we also have seen a surge in areas of the market that were under persistent pressure recently. Consumer Staples have been a big winner, up roughly 10% month-to-date, followed by Health Care. Two of the most defensively oriented sectors are now taking the lead.
The move isn’t limited to just U.S. staples as seen in the heat-map below. Health Care and Utilities are outperforming across most developed regions, while Technology and Communication Services (also dominated by big tech) have become quite weak. Canada is a notable exception as you can see in the heat-map below. Our tech sector has more software and less direct AI exposure. Defensives and rate sensitive, which have struggled in recent months due to rising rates, have quickly reversed course. Energy is the one cyclical sector that is bucking the trend. It’s still strong but has its own idiosyncratic drivers.
Factor performance tells the same story. Low volatility, one of the more forgotten factors this year, has been the best performer over the past month, followed by quality and dividend yield. Momentum and growth have been under considerable pressure. That’s not surprising, since they’re the two factors most closely tied to tech.
Earnings and AI Cracks
It’s still early in earnings season, with just over 10% of S&P 500 companies reported. On the surface, results have been decent. But technology companies, despite beating on both revenue and earnings on average, have been selling off the day after they report. That reflects how high the bar has been set. What has changed is investors’ appetite for spending. Mixed results from Meta and Tesla undermined AI optimism, and the blank-cheque approach to AI capital spending is now being questioned. Investors are getting more selective about the returns they expect for all that capex. The second-order risk is worth watching too. If the AI payoff is slow to arrive, the funding behind much of today’s capex buildout comes under pressure.
It also helps to remember that “the AI trade” is far too broad a label. It covers hyperscalers, neo-cloud companies, chip makers, memory stocks, power producers and more. The biggest winners earlier this year were chips and memory. Korea’s Kospi and the Philadelphia Semiconductor Index became a bubble within the bubble. These indexes were up over 100% YTD in June, but have both now fallen by over 50% from the peak. Markets that move that far, that fast, rarely hold, and the correction in those former leaders doesn’t appear over yet.
Staples: A New Leader?
The surge in Staples in particular is quite telling as the sector has had a very difficult couple of quarters. Since peaking in late February, the sector had fallen 10%. Quite the spell of underperformance versus the S&P 500 which gained 12% over the same time period. Coming into October, valuations were attractive, but sentiment was beaten down. A better-than-expected quarter from bellwether Procter & Gamble helped move the needle and gave investors a reason to act.
But the re-rating has been fast. Staples’ forward P/E went from about 20.6x at the start of the month to just over 23x in a little over three weeks. That’s more than two standard deviations above the sector’s average over the past two years, and surpassed only by the brief spike earlier this year at the outbreak of the war in Iran. Now the question is whether this is just a trade or a trend?
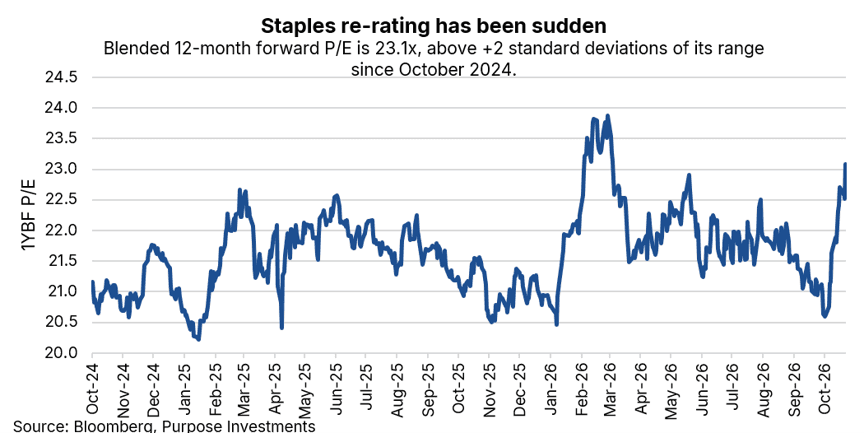
In the near term, valuations look stretched and some giveback wouldn’t be surprising. But what’s pushing money into these defensive segments of the market hasn’t gone away. AI expectations are still lofty, there appears to be rising scrutiny of capex and the market is still extremely concentrated. One month does not make a trend, however from our perspective the shift towards a more defensive mindedness still makes sense.
Final Thoughts
There comes a point in any game, whether football or hockey, when the coach makes an obvious defensive substitution. It usually happens late, when the coach believes a more defensive-minded player gives the team a better chance of holding on to the win.
For our regular readers, this isn’t new, but it’s worth repeating: over the past few months, we’ve been making those substitutions. Markets have had another good year, with most indices up in the mid-teens year-to-date. In our multi-asset portfolios, we’ve been dialing back risk by reducing equity exposure and adding bonds. In our equity mandates, we’ve tried to balance cyclical exposure with higher quality dividend payers. Most recently we have been shifting more towards Staples and oversold rate sensitive areas of the market.
AI capex remains the near-term driver of the macro and overall macro-outlook, but returns on this massive investment remain the open question. Confidence surrounding these returns has become a little shaky. The winds have shifted and while we don’t know how long this will last, it’s a sign that market fragility has increased.
— Derek Benedet at Purpose Investments.
Get the latest market insights in your inbox every week.
Sources: Charts are sourced to Bloomberg L.P., as of October 23.
The content of this document is for informational purposes only and is not being provided in the context of an offering of any securities described herein, nor is it a recommendation or solicitation to buy, hold or sell any security. The information is not investment advice, nor is it tailored to the needs or circumstances of any investor. Information contained in this document is not, and under no circumstances is it to be construed as, an offering memorandum, prospectus, advertisement or public offering of securities. No securities commission or similar regulatory authority has reviewed this document, and any representation to the contrary is an offence. Information contained in this document is believed to be accurate and reliable; however, we cannot guarantee that it is complete or current at all times. The information provided is subject to change without notice.
Commissions, trailing commissions, management fees and expenses all may be associated with investment funds. Please read the prospectus before investing. If the securities are purchased or sold on a stock exchange, you may pay more or receive less than the current net asset value. Investment funds are not guaranteed; their values change frequently, and past performance may not be repeated.
Certain statements in this document are forward-looking. Forward-looking statements (“FLS”) are statements that are predictive in nature, depend on or refer to future events or conditions, or that include words such as “may,” “will,” “should,” “could,” “expect,” “anticipate,” “intend,” “plan,” “believe,” “estimate,” or other similar expressions. Statements that look forward in time or include anything other than historical information are subject to risks and uncertainties, and actual results, actions, or events could differ materially from those set forth in the FLS. FLS are not guarantees of future performance and are, by their nature, based on numerous assumptions. Although the FLS contained in this document are based upon what Purpose Investments and the portfolio manager believe to be reasonable assumptions, Purpose Investments and the portfolio manager cannot assure that actual results will be consistent with these FLS. The reader is cautioned to consider the FLS carefully and not to place undue reliance on them. Unless required by applicable law, it is not undertaken, and is specifically disclaimed, that there is any intention or obligation to update or revise FLS, whether as a result of new information, future events, or otherwise.


